Limited Liability Partnerships

Introduction to Limited Liability Partnerships

A Limited Liability Partnerships (LLP) is a hybrid vehicle. This means it has elements of both a company (legally it is a body corporate and is treated as a separate legal entity from its members: s.1(2) Limited Liability Partnerships Act 2000 (LLPA)) and a partnership (it is treated as tax transparent).

Consequently, an LLP has the flexibility of a partnership with the added advantage of limited liability for its members. Because an LLP is a body corporate, it has a legal personality which is separate to that of its members. As a result, it is liable for its own debts and is able to contract with third parties.

The LLPA was enacted for several reasons, chief of which was the perception amongst professional partnerships that as a result of the growth in litigation, the current partnership model, whilst having many commercially useful features, did not provide the kind of protection that was available to limited liability corporations (this is because partners in traditional partnerships have unlimited liability for the debts of the partnership). Other jurisdictions, such as the USA, had already led the way in dealing with these concerns by creating a hybrid business vehicle and the UK LLP model was drafted along broadly similar lines.

LLPs are increasingly important and many law firms are now run as LLPs. There are approximately 53,000 LLPs registered at Companies House (although this is still a small number in comparison to the number of companies so registered, approximately 4 million).

Applicable legislation

LLPs are incorporated pursuant to the LLPA. The LLPA is supplemented by two statutory instruments: the Limited Liability Partnerships Regulations 2001 (SI 2001/1090) (as amended) (the 2001 Regulations) and the Limited Liability Partnerships (Application of Companies Act 2006) Regulations 2009 (SI 2009/1804) (as amended) (the 2009 Regulations). The 2001 Regulations deal with insolvency and the internal governance of LLPs; the 2009 Regulations govern the corporate law aspects of LLPs. In particular, the 2009 Regulations apply provisions of CA 2006 to LLPs (with appropriate amendments). LLPs are primarily governed by a company (rather than partnership) law framework.

The Insolvency Act 1986 (IA) and the Company Directors Disqualification Act 1986 have, since LLPs were introduced, applied to LLPs in modified form. This has important consequences, so that, for instance, s.213 IA (fraudulent trading), s.214 IA (wrongful trading), as well as the disqualification of director provisions and the greater part of the insolvency and winding up procedures apply equally to LLPs and their members as for companies.

Setting up an LLP

Section 2(1)(a) LLPA states that two or more persons associated for carrying on a lawful business with a view to profit can incorporate an LLP. A ‘person’ in this context can be a company as well as an individual. The use of the word ‘business’ requires that there must be some commercial activity, so LLPs are not normally used by non-profit organisations as business vehicles.

Registration at Companies House

Form LL IN01

The subscribing members fill out a Form LL IN01, which is sent to Companies House with the relevant fee. The form must state, inter alia, the name of the LLP, its registered office’s address and which members, if not all of them, are to be designated members (s.2(2) LLPA).

A copy of a form LL IN01 can be viewed on the www.gov.uk website.

Certificate of Incorporation

Once registered, the Registrar of Companies issues a certificate of incorporation as conclusive evidence that all legal requirements have been complied with. The name of the LLP will be entered on the index of company names and it will be given a number.

Continuing Registration Regime

Once registered, LLPs are obliged to continue to file information with Companies House i.e. change of name, change of registered office, changes in membership, creation of a charge and annual confirmation statement. LLPs are subject to the Limited Liability Partnerships (Accounts and Audit) (Application of Companies Act 2006) Regulations 2008. These require LLPs to file accounts at Companies House.

In addition to its obligations to file information at Companies House, an LLP must maintain certain in-house records, including registers of its members and of its ‘people with significant control’ ([b]PSCs[/b] who are, broadly speaking, those with at least a 25% interest in the LLP).

The LLP Agreement

An LLP has no Memorandum and no Articles of Association. The LLPA and the 2001 Regulations do not lay down any particular management structure to be adopted, in contrast to companies. There is, therefore, greater flexibility with the management of an LLP.

Therefore, it is necessary in practice to have an LLP or Members’ Agreement stating how these issues are to be dealt with by the LLP and its members, in a very similar way to how a partnership agreement is designed to operate.

If there is no Members’ Agreement, various default provisions in regulations 7 and 8 of the 2001 Regulations will apply. Note that any other gaps will not be filled by partnership law, which is disapplied with respect to LLPs by s.1(5) LLPA.

Members of an LLP: Rights and Duties

As referred to in paragraph 4.3 above, the obligations that members of an LLP have to each other are best dealt with in a formal written Members’ Agreement. Such an agreement is a private document and would set out formal procedures and arrangements to which the members had agreed.

However, members of an LLP are not obliged to have a formal Members’ Agreement to regulate their relationship and in the absence of any such agreement, the 2001 Regulations contain eleven default provisions as set out below.

Regulations 7 and 8 of the 2001 Regulations

  • Members share equally in capital and profits (Reg.7(1)).
  • An LLP must indemnify its members for payments made and personal liabilities incurred by them in the ordinary and proper conduct of the business of the LLP (Reg. 7(2)).
  • Every member may take part in management (Reg.7(3)).
  • No member is entitled to remuneration for managing the LLP (Reg.7(4)).
  • No person can become a member or assign their membership without the consent of all existing members (Reg.7(5)).
  • Ordinary decision making may be by the majority of the members. Any proposed change to the nature of the business requires the consent of all the members (Reg.7(6)).
  • The books and records of the LLP must be available for inspection by the members at the registered office (Reg.7(7)).
  • Each member must give true accounts and full information of all things affecting the LLP to any member or his legal representative (Reg.7(8)).
  • If a member (without consent) carries on any business of the same nature as, and competing with, the LLP then he must account for and pay over to the LLP all profits made by him in the business (Reg.7(9)).
  • Every member has a duty to account for benefits derived from transactions with the LLP and its business or property (Reg.7(10)).
  • There is no implied power of expulsion of a member by the majority unless the members have expressly provided for such a power in a Members’ Agreement (Reg.8).

Members

The members of an LLP are those who subscribed to the incorporation document and those who became members at a later date by agreement with the existing members. Section 4(2) LLPA provides that persons, not just individuals, can be members of an LLP. Therefore, corporate bodies may be members of an LLP.

An LLP must have at least two formally appointed members at all times. There is no limit on the maximum number of members an LLP can have.

At least two members of the LLP must be ‘designated members’. Their obligations include, amongst other things, appointing an auditor, signing the accounts on behalf of the members, making filings at Companies House and acting on behalf of the LLP if it is wound up.

Section 4(3) LLPA states that a member will cease to be a member of the LLP upon:

  • his death;
  • agreement with the other members of the LLP;
  • giving notice to the other members of the LLP; or
  • dissolution (if the member is a body corporate).

Summary of the Characteristics of LLPs

LLPs are a hybrid form of a partnership and a company, taking characteristics from both forms of business media.

Corporate Characteristics:

  • separate legal personality;
  • limited liability for members, subject to the restrictions mentioned above;
  • LLPs have to file accounts at Companies House on much the same basis as companies, leading to a loss of financial privacy (which is one of the main attractions of using a partnership structure);
  • LLPs, like companies, are capable of creating a floating charge (an important type of security interest) over the assets of the LLP, unlike a partnership; and
  • some provisions of company law (in particular CA 2006) and corporate insolvency law (as contained in the Insolvency Act 1986 and the Company Directors Disqualification Act 1986) apply to LLPs in modified form.

Partnerships Characteristics:

  • LLPs have no share capital or capital maintenance requirements;
  • no real distinction between members and the management board (unlike a company, in which the members/shareholders and board of directors have very distinct roles);
  • members can agree amongst themselves how to share profits, management duties, how decisions are to be made, how new members are to be appointed and what retirement provisions shall apply;
  • the Members’ Agreement (if there is one) is like a partnership agreement, i.e. a private document which need not be filed at Companies House; and
  • although broadly, as stated above, the corporate insolvency regime also applies to LLPs, there exists an important disadvantage for members of an LLP compared to those of a company. LLPs are subject to the ‘clawback’ rule, which means that in certain circumstances money taken out of the LLP by members up to two years before commencement of a winding up of the LLP can be clawed back into the pool of assets available to repay LLP’s creditors (s.214A IA). By contrast, no equivalent provision applies if a shareholder disposes of shares in a company.

Taxation of LLPs

One important difference between an LLP and a company is that, for tax purposes, the LLP is treated as a partnership.

If two individuals set up an LLP, each will be taxed as an individual, i.e. liable to income tax or capital gains tax on their share of the income or gains of the LLP. In other words, an LLP is ‘transparent’ for tax purposes. This means the LLP is not taxed but the partners are.

By contrast, a company, established by the same two individuals, would pay corporation tax on its own income profit and chargeable gains. If the individual owners then receive dividends out of the company’s profits (after corporation tax), they may be liable to pay income tax on their dividend income. This could be significant, for example, because different rates and reliefs might apply.

A trade, profession or business carried on by an LLP with a view to profit will be treated as being carried on in partnership by the members (not the LLP itself). Many of the same reliefs available to partners also may be available to LLP members, such as relief on interest or set off of losses against other income.

Assets held by the LLP will be treated as being held by the members as partners for capital gains tax purposes. Accordingly, a disposal of an LLP asset, such as land, will be regarded by HMRC as a disposal by the members of the LLP while it is trading.

The LLPA gives relief from stamp duty where a partnership is incorporated as an LLP and assets of the partnership business are transferred to the LLP, subject to strict tax avoidance conditions. In some circumstances, stamp duty and/or SDLT is payable on the transfer of an interest in an LLP at the relevant rate.

As regards VAT, the LLP itself may register for VAT, not the members.

Commercial Uses for LLPs

Apart from being more and more commonly used for professional partnerships, such as solicitors, surveyors or accountants, it is also a flexible business vehicle for joint ventures, certain investment schemes and some venture capital
investments.

LLPs are particularly useful for investment structures (despite certain tax avoidance measures being applicable to LLPs which may impinge on private investors who are members of an LLP). This is because, as stated, LLPs are tax transparent, so they allow a high level of participation in management by the members whilst giving the members the benefit of limited liability. Furthermore, there is no need for a ‘general partner’’ with unlimited liability, in contrast to a limited partnership.

LLPs are increasingly being used by property developers involved in one-off joint venture development projects.
Limited Partnerships

Introduction to Limited Partnerships

Limited Partnerships (LP) are formed and regulated in accordance with the Limited Partnerships Act 1907 (LPA) (although common law and the PA 1890 are still applicable to LPs). Essentially, an LP is an ordinary partnership but with certain modifications under the LPA.

The main difference between an ordinary (traditional) partnership and an LP is that some partners in an LP have limited liability for the debts and obligations of the partnership. Like partnerships (but unlike LLPs), LPs are not separate legal entities.

The PA 1890 applies to LPs except where inconsistent with the LPA. For example, if there is no agreement as to a profit sharing ratio, all partners share equally under s.24(1) PA 1890.

LPs require the involvement of at least two partners:

  • at least one general partner; and
  • at least one limited partner.

Nature of liability

A general partner’s liability is always unlimited. This reflects the fact that the general partner manages the business.

Limited partners have limited liability, up to the amount of their contribution to the LP (s.4(2) LPA). Importantly, however, this only applies if they are not involved in the day-to-day management of the partnership (s.6 LPA).

This makes LPs a useful vehicle for investment funds, where the general partner manages the fund and investors are protected from any liability by becoming only limited partners.

Roles of general and limited partners

The LPA does not describe what the general partners may do. Rather it focuses on what the limited partners cannot do. For example, the limited partners have no power to bind the firm. It is important that the management of the business is in the hands of the general partner(s) only. (Contrast the position of an ordinary partnership where management is in the hands of all the partners under s.24(5) PA 1890). If a limited partner takes part in the management of the partnership business he shall be liable for all debts and obligations during this period as if he were a general partner (s.6(1) LPA).

A general partner in a limited partnership is more akin to a managing director than to an ordinary partner on equal terms with the other partners.

The limited partners must agree before any changes are made to matters such as profit share, expulsion of partners, alteration in the nature of the partnership business and variation in the partnership agreement. These cannot be changed by the general partner alone.

Registration of LPs

LPs must be registered at Companies House under ss.5, 8 and 8A LPA. Limited partners in an LP that fails to be correctly registered forfeit their limited status and will be treated as partners in ordinary partnerships.

The information which needs to be filed (and updated when it changes) by an LP includes the firm’s name, the general nature of its business, the principal place of business, the names of the partners and the sum contributed by any limited partner (s.9 LPA). Under s.8B LPA all new limited partnerships must expressly include ‘Limited Partnership’ or ‘LP’ or the equivalent at the end of their names. The Registrar is required to issue a certificate of registration as conclusive evidence that the LP has been formed and registered (s.8C LPA). As with the Companies Register, the register of LPs is available for public inspection. LPs are registered with form LP5, which can be viewed on the www.gov.uk website.

Importantly, an LP need not file annual accounts or confirmation statements.

Dissolution of LPs

A limited or a general partner may dissolve the LP under a provision in the partnership agreement and the law relating to ordinary partnership dissolution will generally apply to LPs. One exception is that a limited partner may not dissolve the LP by notice if the LP is a partnership at will, without agreement from all the other partners (a general partner may however do so (s.6(5) LPA)).

Use of LPs

You may encounter LPs only rarely in practice unless you work with venture capital funds, private equity or real estate investment vehicles, which are often run through LPs.

In a venture capital partnership, investors (the limited partners) advance money, to be placed for them by the general partner (often referred to as a manager) in commercial ventures in need of finance. The manager will charge a fee and will receive a share of the profit. The LP vehicle is suitable as the majority of investors in a venture capital fund are passive investors and will not participate in the management of the fund.

LPs are the vehicle of choice for private equity fundraising. They are tax transparent and highly flexible: the partners can write their own internal partnership rules without having to conform to the detailed requirements of CA 2006.

In recent years, the limited partnership regimes in other jurisdictions have become more attractive to fund managers. The Treasury proposed a number of reforms to the UK regime to improve the UK’s competitiveness in this market. As a result, in April 2017 a new sub-type of LP, the Private Fund Limited Partnership (PFLP), was created (under the Legislative Reform (Private Fund Limited Partnerships) Order 2017) to reduce some of the administrative burdens on private investment funds which are structured as LPs.

Taxation of Partnerships

Each partner is liable to tax as an individual on his share of the income or gains of the partnership. This is described as tax transparency.

Even though a partnership is not a distinct legal entity, HMRC requires a partnership to make a single tax return of its profits which must be agreed with HMRC (as with sole traders, partnerships choose their own accounting period). Partners submit their own individual tax returns containing all income received from the partnership as well as other income receipts (including, for example, from savings, dividend and/or rental income).

Each partner is personally liable for the tax on his share of the partnership profits. Unlike with other partnership liabilities where each partner is jointly and severally liable, a partner is not liable for the tax on other partners’ shares of partnership profits.

Normal capital gains tax principles apply on disposal of a capital asset by a partnership. Each partner is treated as owning a fractional share of the asset. On disposal by the partnership, each partner is treated as making a disposal of his fractional share and will be taxed on this fractional share of any gain, subject to the availability of any reliefs available to individuals. A partner’s fractional share shall be based upon the agreed PSR or, if there is no agreed PSR, then equally in accordance with s.24(1) PA 1890.

Termination of a partnership

Partner leaving

If there is no partnership agreement or if the agreement is silent on retirement or termination (i.e. there is a ‘partnership at will’), the effect of a partner leaving is that the partnership is dissolved (see s.26 PA 1890). This is because ‘partnership’ is a collective noun meaning ‘all the partners’ and so the continuity of a partnership is broken when there is a change in the identity of the individuals who constitute it. In most cases this is a ‘technical dissolution’. This means that a new partnership is formed by the remaining partners who continue the business. However, it is open to any of the partners to apply to court to have the old partnership wound up (i.e. sale of the assets for the repayment of the partnership debts and for the distribution of the assets or liabilities amongst the partners).

To prevent dissolution when a partner leaves, the partnership agreement should state explicitly that the partnership will continue as between the remaining partners and should contain details of how a partner can leave (which may include a provision in the event of death) or be expelled without the partnership being wound up. This would usually include a mechanism for the remaining partners to buy out a departing partner’s share.

Dissolution of partnership

A partnership can be dissolved in a number of ways:

  • automatic dissolution under s.32(a) and (b) PA 1890 (expiry of fixed term/completion of specific venture), s.33 PA 1890 (death or bankruptcy of partner) or s.34 PA 1890 (if the partnership business becomes unlawful). The provisions of ss.32 and 33 are subject to contrary agreement;
  • dissolution of partnership at will (i.e. with no fixed duration) by notice from any partner (ss.26 and 32(c)); and
  • dissolution by the court as a last resort under s.35 PA 1890.

If an event occurs which causes a partnership to be dissolved, the partnership relationship ceases and any partner may demand that the assets of the business are realised.

Winding up partnership: Collecting in/distributing assets (s.44 PA 1890)

Subject to any written partnership agreement, where a partnership is wound up, once all debts and liabilities have been paid, any money/assets left will be distributed so that each partner is paid back his/her original capital first (s.44(b)(3)). It is common for a partnership agreement to have a provision dealing with the proportion in which any surplus assets are to be shared out following dissolution. This is called the asset surplus ratio or ‘ASR’. If there is no agreed ASR then s.44(b)(4) applies and surplus assets are shared in accordance with the agreed profit sharing ratio PSR. If there is no PSR then they are shared equally in accordance with s.24(1) PA 1890.

Personal liability for partnership debts

Because a firm has no legal personality separate from the partners, the partners are personally bound under, and hence liable on, contracts which are binding on the firm. The PA 1890 contains provisions relating to the nature and extent of such liabilities. In some circumstances, non-partners can also become personally liable.

Nature of partners’ liability (ss.9, 10 and 12 PA 1890)

Contractual Liability: Every partner in a firm is liable jointly with the other partners for all the debts and obligations of the firm incurred whilst he is a partner (s.9).

Tortious Liability: In tort the partners’ liability is joint and several (ss.10 and 12).

Liability of non-partners: new and former partners (ss.17 and 36 PA 1890)

Under s.17(1) a new partner will not automatically be liable in relation to any debts incurred by the partnership before he joined.

Under s.17(2) a partner will still be liable after he retires in respect of debts incurred by the partnership whilst he was a partner. In order to relieve a partner from an existing liability once he retires, a partnership may novate the relevant agreement; this must be with the consent of the creditor (s.17(3)).

It is also possible for a former partner to become liable for new partnership debts incurred after he has left under s.36. If a partner leaves, a third party can treat all apparent partners of the firm as it was before the change (i.e. including the departing partner) as jointly liable to pay any new debt incurred by the partnership UNLESS that third party has been notified of this change either by:

  • actual notice (s.36(1)) – for those who have had actual dealings with the partner before departure; or
  • constructive notice by virtue of publication of the departure in the London Gazette (s.36(2)) – for those who have not had actual dealings with the partner before departure.

However, a former partner will not be liable for debts to any third party who did not know him to be a partner before he left. No notice at all has to be given to such persons.

Liability of non-partners: ‘holding out’ (s.14 PA 1890)

Generally, a person who is not a partner has no personal liability for partnership debts. However, s.14 sets out circumstances where a non-partner may be personally liable on a partnership debt if he has held himself out as a partner (or has knowingly allowed himself to be so held out).

The elements required for s.14 to have effect are (i) a representation to a third party to the effect that a person is a partner, (ii) the third party’s action in response (‘giving credit to the firm’, e.g. by supplying goods or services to the firm) and (iii) the third party’s state of mind (‘believing (having faith in) the representation’).

It is important to appreciate that s.14 relates to the liability incurred by the NON-PARTNER, not the liability of the firm. The liability of the firm for the acts of a non-partner is established by applying the common law principles of agency.

The relationship between the firm and outsiders: contracts binding the firm

In practice, you may need to decide whether or not the partnership is bound by a contract which an individual has purported to make on its behalf. In a partnership context, the approach to answering the question of whether or not a firm is bound by a particular contract will differ depending on whether the individual acting on the firm’s behalf is a partner or not. This is because s.5 PA 1890 introduces a special statutory rule of agency which applies only when the agent in question is a partner in the firm. Where the purported agent is not a partner, you apply rules from the common law. We will consider each of the ‘partner’ and ‘non-partner’ approaches separately below.

Partners content with agent’s act (whether partner or non-partner)

In many cases, an individual acting as a firm’s agent (whether a partner or not) will simply have put into effect the wishes of the partnership as a whole. If all the partners are happy for the firm to enter into the contract and have given actual, express or implied authority to bind the firm, then the firm will be bound. In any event, if the partners are happy to be bound, the situation is not problematic even if the agent had no authority at the time the contract was made. The partners are able to ratify the agent’s act and adopt the contract, either expressly or simply by going ahead and performing it.

Partners not content with agent’s act

Either s.5 PA 1890 or the common law rules of agency will determine whether or not the firm is bound, depending upon whether the agent is a partner or not.

Power of a partner to bind the firm against the partners’ wishes: s.5 PA 1890

Section 5 makes provision for the firm to be bound in certain circumstances, even where the other partners are not happy to be bound by the contract made by the agent. Since s.5 is intended to protect the third party to the contract, it is that third party’s view of what is happening that counts.

Following s.5, a partner’s unauthorised act will bind the firm if, viewed objectively:

  • the act is for carrying on business of the kind carried on by the firm (for example, “is this the kind of contract that one would expect to be done in the course of business of this kind?”); and
  • the act is for carrying on such a business in the usual way (for example, “is this the kind of contract that a partner acting alone would usually make on the firm’s behalf or is it a contract of the kind an outsider would expect all partners in a firm to sign individually?”).

The firm will not be bound, however, if:

  • the third party actually knew that the partner in question was not authorised to enter into the contract on behalf of the firm; or
  • the third party did not know or believe that the partner was a partner.

A partner who binds his firm without actual authority may be liable to the other partners for breach of contract.

Power of a non-partner to bind the firm against the partners’ wishes: apparent authority at common law

Section 5 does not apply at all if the person entering the contract is not in fact a partner. In that case, the common law rules of agency establish whether or not the firm is bound as principal.

At common law, an agent who has no actual authority may still bind the firm if he has apparent authority to enter into a contract. Apparent (sometimes called ‘ostensible’) authority arises when the principal (here the firm) represents or permits a representation to be made to a third party that a person has authority to bind the firm. For example, if a firm employs somebody under the title ‘marketing manager’, that title confers on that person apparent authority to bind the firm on marketing decisions. Once the principal’s representation has been made to, and relied upon by, the third party, the principal is bound by the actions of that person.

If the representation is that a particular person is a partner (when, in fact, they are not), then the firm is said to be ‘holding out’ that person as a partner. A person who has been held out as a partner has apparent authority to bind the firm in the same way as a real partner can. An example of holding out is in relation to an ex-partner, when the firm carries on using old letterhead (including his or her name) after he or she retires.

Section 5 is always the first place to look when deciding whether or not an act of a partner binds a firm but does not displace the application of ordinary common law agency entirely. In some circumstances, s.5 alone will not get you to the end of the story. If a partner has purported to form a very unusual kind of contract on behalf of the firm, a s.5 analysis may lead you to conclude that the firm is not bound under statute. However, the particular facts and circumstances of the case may mean that this partner did have his partners’ apparent authority at common law to conclude the contract.

Relationship of partners to one another

The Partnership Agreement or Deed

Most partnerships will have some form of express agreement. As a minimum, this will normally include provision for sharing the profits and, on dissolution, the capital. It will usually also provide for the joining of new partners, the retirement of existing partners and termination of the partnership.

The PA 1890 contains a default code, which applies to relations between the partners themselves in the absence of any contrary agreement.

The partners’ mutual rights and obligations (under an agreement or under PA 1890) can be varied at any time by their unanimous consent (s.19 PA 1890) and this can be express or inferred from a course of dealing. Clearly it is preferable for any such agreement to be expressly and properly documented for certainty.

‘Fall back’ provisions on internal affairs

PA 1890 contains provisions dealing with the internal regulation of the partnership. These are subject to any agreement, express or implied, between the partners. The fall back provisions include the following:

  • S.24(1) Profits: Partners are entitled to share equally in the profits of the business. This is the case even where the parties have contributed to the capital unequally. There should therefore be an express provision in the agreement setting out a profit sharing ratio (PSR), otherwise profits and losses are shared equally, which may not be desirable if one partner has invested more (or less) in the partnership than the others.
  • S.24(6) Remuneration: Without an agreement a partner is not entitled to a salary.
  • S.24(8) Decision Making: Decisions arising during the ordinary course of the business are decided by a majority, except for any change to the nature of the partnership business which requires unanimity.
  • S.25 Expulsion: A partner cannot be expelled by majority vote unless all of the partners have previously expressly agreed that a majority can do this. The partners should therefore agree expulsion provisions in advance, otherwise it will be impossible to remove a partner without dissolving the partnership.

Partnership property

As a partnership does not have a separate legal personality, each partner is deemed to own a share in the property belonging to the partnership. An individual partner does not have a right to any particular partnership asset.

Section 20 PA 1890 provides that all property brought into the partnership whether by purchase or otherwise, on account of the firm or for the purposes and in the course of the partnership business, is partnership property. Whether or not a particular asset is partnership property is a question of fact, depending on the intentions of the partners at the time they acquire it. This subjective element can be difficult to prove and so it is sensible for partners to agree which assets are partnership property to minimise the potential for dispute later.

Section 21 PA 1890 provides that all property bought with money belonging to the firm/partnership is deemed to have been bought on account of the firm/partnership, unless the contrary intention is shown.

Fiduciary relationship

There is an overriding duty of good faith in a partnership. The duty owed by the partners to one another is similar to that owed by a trustee to a beneficiary. These equitable principles are reflected in the following sections of the PA 1890:

  • Honest and full disclosure (s.28 PA 1890)
  • Unauthorised personal profit (s.29(1) PA 1890)
  • Conflict of duty and interest (s.30 PA 1890).

General partnerships

In practice, you will sometimes find that clients ask for your help to avoid creating a partnership, rather than asking you to create one for them. One reason for this is that the legislation governing partnerships is over 100 years old and the default provisions, which will be implied by that legislation, are often unsuited to the modern business environment. Additionally, clients may have concerns about being subject to unlimited liability.

Nevertheless, there are some advantages. For example, it costs nothing to create a partnership, because no formality is required to create one. In fact, there are almost as many partnerships in the UK as there are companies and many of them are professional partnerships such as lawyers, accountants, surveyors and architects. Many businesses start as partnerships before they convert to a limited company.

The Partnership Act 1890 (PA 1890)

The PA 1890 provides the framework for regulating traditional partnerships. However, there is case law to supplement the PA 1890, and I will cover a small number of cases in later posts.

Whilst the PA 1890 and case law provide a framework for governing traditional partnerships, they are really ‘fall-back’ provisions in the absence of a partnership agreement or where the agreement is silent on any matter. Most traditional partnerships will have a formal written partnership agreement.

Existence of partnerships

As mentioned previously, a partnership is a relationship between persons carrying on a business in common with a view of profit (s.1(1) PA 1890).

Section 2 PA 1890 contains a list of rules for determining the existence of a partnership. The purpose of s.2 is to provide more detailed guidance in determining if the criteria in s.1(1) have been met. For example, evidence of profit sharing will be prima facie evidence of a partnership but not necessarily conclusive evidence (s.2(3) PA 1890). Case law provides that if there is an agreement to share losses as well as profits this makes the existence of a partnership more likely (Northern Sales (1963) Limited v Ministry of National Revenue (1973)). A loan of money by one party to another does not create a partnership.

Case law has also held that if the person is not being “held out” as a partner this makes the existence of a partnership less likely. In Walker v Hirsch (1884) a clerk lent money to the partnership, was paid a fixed salary and took 1/8th of the profits and of the losses but was never held out as a partner. No partnership was found to exist.

Partnerships, Limited Partnerships & Limited Liability Partnerships

Introduction to partnerships

I briefly touched on the different types of businesses entites in my posts about business taxation, where we looked at sole traders, partnerships and limited companies. Over the next series of posts, we will look in depth at the different types of partnerships that exist.

We will consider three different types of partnerships:

  • The traditional partnership, which is governed by the Partnership Act 1890, which contains the basic structure of partnership law. this type of partnership is often known as a ‘general partnership’. The partners in a partnership of this type have unlimited liability for the debts and obligations of the partnership.
  • The Limited Partnership (LP), which was introduced by the Limited Partnership Act 1907. Provided one partner is the general partner and therefore accepts unlimited liability, all of the other partners (known as the limited partners) can benefit from limited liability. The limited partners must not be involved in the day-to-day running of the partnership business (otherwise they lose their limited liability status). For this reason, LPs are often used in fund structures. The limited partners are passive investors with no active role in managing the partnership business.
  • The Limited Liability Partnership (LLP), which was introduced by the Limited Liability Partnerships Act 2000. LLPs are often described as hybrids as they combine elements of both a partnership and a company. They have the flexibility of conventional partnerships in relation to their internal arrangements but they are treated as single legal entities with limited liability of their own. LLPs are subject to many provisions of the Companies Acts (and most particularly the Companies Act 2006).

Business Strategy

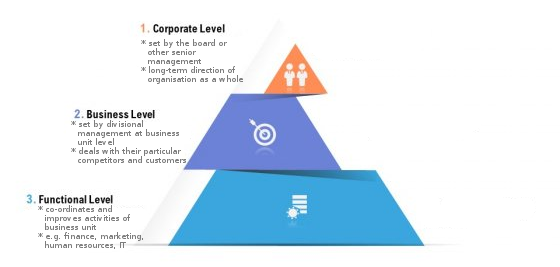
Over the past couple of posts, I have looked at different types of business analysis. Of course, analysis is only part of the picture of business management, there is also a strategic process. Strategy goes on at all levels of an organisation all the time. As the diagram below shows, strategies can exist at corporate, business or functional levels.

Most large businesses have a clearly verbalised mission which rarely changes and any strategic work that they do on a day-to-day basis will be focused on achieving this mission. Therefore, modern businesses are very aware of strategic alignment. This simply means that any strategic activity which takes place which is not at the level of changing the overall strategy or mission of the business needs to align with the bigger picture which already exists.

Businesses often suffer the basic structural dilemma of how much autonomy to allow lower order units in implementing the overall strategy. For example, the question of how much independence the main board gives subsidiary boards in implementing their strategies.

Organisations can either deal with this dilemma by centralising the decision making processes or decentralising it so that the managers at each business unit make the decisions. This will be a significant consideration for you when dealing with clients that are business units or larger organisations as to identifying who the actual decision makers are.

The more clear employees and customers are on what a business stands for and how things are ‘done around here’, the quicker the business can react to changes because there is a better instinctive understanding of what to do. This is really important in large businesses, because it is not possible to seek consensus on every decision from every level of the organisation. As long as senior management has made it clear what the business’ overall strategy is and how this works in practice, employees can be fairly comfortable, when making decisions that affect the organisation that they are acting in a way which reflects, rather than conflicts with, this overall strategy.

Legal professionals involvement in businesses

Much of the advice that businesses seek from legal firms will be as result of strategic change or activity. Often, managers will require legal advice in connection with the implementation of their plans. Some examples of such situations may be:

  • managers may need advice about new contracts with suppliers, staff or customers;
  • businesses may want help with acquiring property, other businesses or entering into a joint venture;
  • a referral to the Competition and Markets Authority;
  • a recession may have led to the need to make staff redundant;
  • setting up a new business vehicle to enter into a new marketplace; and
  • understanding the legislation to set up a new division of the business overseas.

For all of these reasons, and many more, lawyers are an essential part of the business process, particularly where strategic activity is involved. As such, having a good understanding of this area will ensure that you are able to provide appropriate, considered, timely and cost efficient advice.